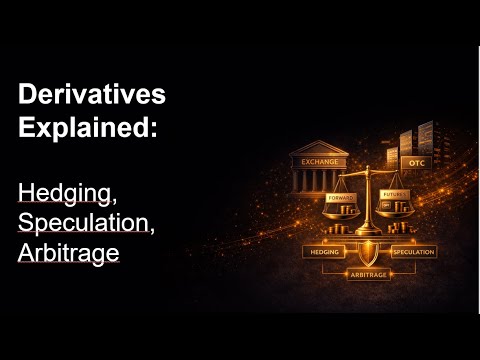
Derivatives: what they are and how they work (complete guide)
Educational and informational content only. Not personalized advice, a recommendation, or a solicitation. Derivatives are complex instruments and can lead to losses exceeding the capital invested.
Introduction: what "derivative" means
A derivative is a contract whose value derives from the movement of something else, the underlying: a stock, an index, a commodity, an interest rate, a currency. You don't buy the asset itself: you buy (or sell) an agreement about how its price will behave by a given date. This is what every derivative — forward, future, option, swap — has in common, beyond the technical differences.
Why do they exist? Originally for a single reason: to transfer risk from someone who doesn't want it to someone willing to take it on. The farmer who locks in today the price of next season's wheat is protected against a fall; the party on the other side takes on that risk. From this core come the three uses we'll cover: hedging, speculation, arbitrage.
Every published episode, each with a companion note (key concepts, worked example, risks), is on the Derivatives series page.
The four building blocks
- Forward — a private agreement to buy/sell the underlying at a price and date fixed today. Flexible but "bespoke": you pay for it in counterparty risk. How its price is set → see episode 5, the cost of carry.
- Future — the standardized, exchange-traded forward, with a clearing house that steps in and removes the risk of the counterparty failing to pay. → see Futures — Part 1: how they work.
- Option — gives the right, not the obligation, to buy (call) or sell (put) the underlying at a preset price. The buyer pays a premium; the seller collects the premium but takes on the obligation. → see episodes 8, 9 and 10 of the series.
- Swap — an exchange of cash flows over time (e.g. fixed vs floating rate, or two currencies). It's the building block under much of corporate and bank finance. → see episode 7.
Where they trade: regulated markets vs OTC
- Regulated market (exchange): standardized contracts, transparent prices, a clearing house guaranteeing positions. This is the world of futures and many options.
- OTC (over-the-counter): bilateral, bespoke contracts negotiated off-exchange. Maximum flexibility, but the risk of the counterparty defaulting is on you — the lesson of Lehman Brothers (2008) was born exactly here. Covered in episode 1 of the series.
What they're actually for: the three purposes
- Hedging — reducing a risk you already have. Example: a European exporter who'll receive dollars in six months can lock in the exchange rate today with a forward, removing currency uncertainty. (Same mechanism behind "hedged" ETFs → see Currency hedging: hedged vs unhedged ETFs.)
- Speculation — taking on risk to seek a profit from an expected move. Leverage amplifies gains and losses: this is where derivatives become dangerous if used without understanding them.
- Arbitrage — exploiting price misalignments across markets for a theoretically risk-free profit. In practice the windows are tiny and close fast.
Derivatives for the retail saver: certificates and covered warrants
On the retail market, derivatives arrive "packaged": certificates and covered warrants are securitized instruments issued by banks, with very different risk, tax and efficiency profiles. Understand them before touching them. → see Certificates and covered warrants: what they are and how they're taxed.
Mistakes and risks to know
- Leverage = a small move in the underlying becomes a large move in your capital, in both directions.
- Counterparty risk (especially OTC) = the contract is worth as much as whoever sold it to you.
- Complexity = a misunderstood derivative is a misunderstood risk. Educational rule: if you can't explain its payoff, you're not ready to use it.
Conclusion
Derivatives are neither good nor bad: they're risk-transfer tools. The same future that protects a company can ruin a leveraged speculator. The difference is understanding.
Continue the derivatives series
- The full video series, with a note for every episode
- The eight key steps of the series, from futures to Black-Scholes
- Futures — Part 1: how they work (margins, mark-to-market, leverage)
- Futures — Part 2: hedging properly (hedge ratio and basis risk)
- Certificates and covered warrants
Sources
Borsa Italiana — Glossary · CONSOB — derivatives education · J. Hull, Options, Futures and Other Derivatives · BIS — OTC market statistics.
This information is for educational purposes only. It is not a recommendation or personalized advice. Past performance does not guarantee future results.